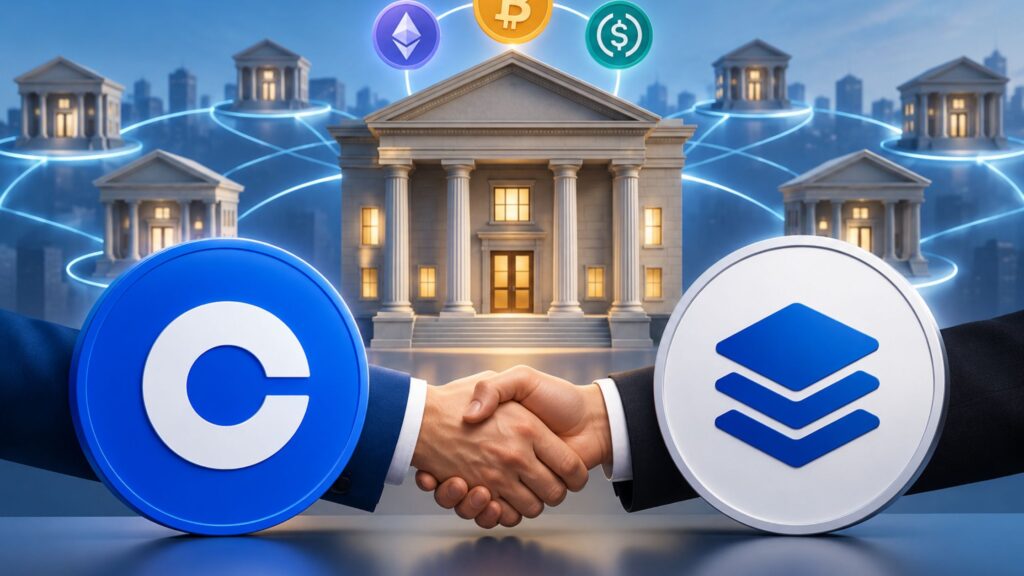
The Stablecore crypto deal could expand access to digital assets across thousands of U.S. banks and credit unions. Announced on September 16, the partnership combines Coinbase’s infrastructure with Stablecore’s banking technology, allowing institutions to offer digital asset services through existing apps. Banks could provide trading, custody, staking, and stablecoin payment features within banking apps.
How the Coinbase Stablecore Crypto Deal Works
The partnership divides responsibilities. Banks and credit unions maintain customer relationships, branding, and account services. Stablecore connects digital asset functionality with core banking, digital banking, and compliance systems. Coinbase provides custody and exchange infrastructure.
This model can reduce technology burdens for financial institutions. Customers could potentially buy, sell, hold, stake, and use digital assets without a separate Coinbase account. Stablecore’s white-label approach lets institutions retain their own interfaces while external infrastructure operates behind the scenes.
What the 3,000+ Figure Means
The headline figure needs context. Stablecore says its existing technology integrations reach more than 3,000 U.S. banks and credit unions. However, that does not mean 3,000 institutions have signed agreements with Coinbase or will automatically activate services.
Each institution must decide which products to offer based on technology, business strategy, regulatory requirements, and internal policies. Amarillo National Bank in Texas has been identified as an early integration partner. The companies have not disclosed deployment numbers, transaction volumes, or a customer launch date.
Compliance and Monitoring
Stablecore also announced a partnership with Nasdaq Verafin, a financial-crime monitoring platform used by thousands of financial institutions. The arrangement strengthens monitoring for digital asset transactions.
Stablecore can hold transaction and position information without storing personally identifiable information. Banks retain customer and account records within their core systems. Relevant information can then flow into Verafin for investigation and risk assessment. Amarillo National Bank is a beta tester, while rollout is planned for late 2026 and early 2027.
Regulatory Background
The Coinbase Stablecore crypto deal arrives amid evolving U.S. banking guidance for digital assets. Recent OCC and Federal Reserve actions have clarified aspects of custody, customer-directed transactions, stablecoin activities, and third-party arrangements.
These developments may give eligible institutions more pathways to provide services. However, regulatory permission does not create an automatic nationwide offering. Charter type, state requirements, risk controls, and individual bank policies can determine which products become available.
Coinbase Expands Community Banking Reach
The Stablecore agreement follows Coinbase’s September partnership with Moov, targeting stablecoin payment acceptance, merchant settlement, and real-time funding across a network of more than 1,000 community banks and credit unions.
Together, these deals show how Coinbase is pursuing banking distribution through partnerships. The Coinbase Stablecore crypto deal covers trading, custody, and staking, while the Moov relationship emphasizes payment infrastructure. This approach could let local institutions offer digital asset services while maintaining customer relationships.
What It Could Mean for Customers
If participating banks activate available features, customers may gain simpler access to digital assets through platforms they already use for financial services. For banks, embedded infrastructure could reduce development requirements and connect existing accounts with emerging payment and investment products.
Availability will vary between institutions. Customers should check their bank’s product disclosures, fees, supported assets, custody arrangements, and restrictions before using any service.
Conclusion
The Coinbase Stablecore crypto deal marks another step toward integrating digital assets with community banking infrastructure. Its reach of more than 3,000 connected institutions should not be confused with confirmed customer adoption. Impact will depend on participation, regulation, launches, and customer demand. For now, the partnership highlights Coinbase’s growing role as an infrastructure provider behind bank-based digital asset services.